Published: Thursday, 17 September 2026, at 1:36 am| Dubai | Edited: Thursday, 17 September 2026, at 1:45 am
Managing my finances in the Gulf taught me that learning how I improve my AECB credit score in UAE is crucial for unlocking hassle free loans, credit cards, and apartment rentals. Read on to discover everything you need to know about understanding your credit report, boosting your score, and avoiding financial pitfalls.
ALSO READ:
- UAE Bank Loan Relief 2026: Temporary Relief for Over 135,000 Customers
- UAE Personal Loan Guide 2026: Latest Central Bank Rules, Top Bank Options, and Eligibility Criteria
- UAE Credit Card Guide 2026: The Smart Way to Choose Between Cashback, Air Miles, and Free Cards
How I Improve My AECB Credit Score in UAE: Complete Financial Blueprint
When I first arrived in Dubai, I did not realize how heavily banks, landlords, and telecom providers rely on credit ratings. Learning how I improve my AECB credit score in UAE helped me secure lower interest rates and quick financial approvals across the Emirates. Let us dive into the details to help you build a stellar financial profile today.
- Score Provider: Al Etihad Credit Bureau (AECB)
- Score Scale: 300 to 900 score range
- Ideal Score Target: 700+ for premium credit approvals
- Key Factors: Payment history, credit utilization, and debt mix
Understanding AECB and Its Function in the UAE
A complete overview of the credit bureau and its role in evaluating resident financial health.
The Al Etihad Credit Bureau (AECB) is a federal government entity that collects financial data from banks, telecom operators, and utility companies across the UAE.
- Data Aggregation: AECB gathers financial records from banks, DEWA, Etisalat, and du.
- Risk Evaluation: Financial institutions evaluate your credit report to judge repayment risk.
- Central Database: The bureau maintains financial histories for all UAE citizens and expats.
Why Your Credit Score Matters in Daily Life
How your rating impacts loan approvals, rental contracts, and job checks.
During my journey, I discovered that your credit rating affects far more than just standard credit card approvals.
- Bank Approvals: High scores secure lower interest rates on personal, car, and home loans.
- Credit Limits: Banks offer higher credit card limits to customers with strong financial health.
- Rental Agreements: Landlords check credit scores before approving residential lease contracts.
- Employment Checks: Employers in finance and government sectors review credit profiles during hiring.
ALSO READ:
- Which Are the Best Banks in the UAE for 2026?: A Complete Guide on Savings Rates, Fees, and Perks
- Minimum Salary for Personal Loan in UAE (2026 Guide): Real Requirements, Tips & Approval Secrets
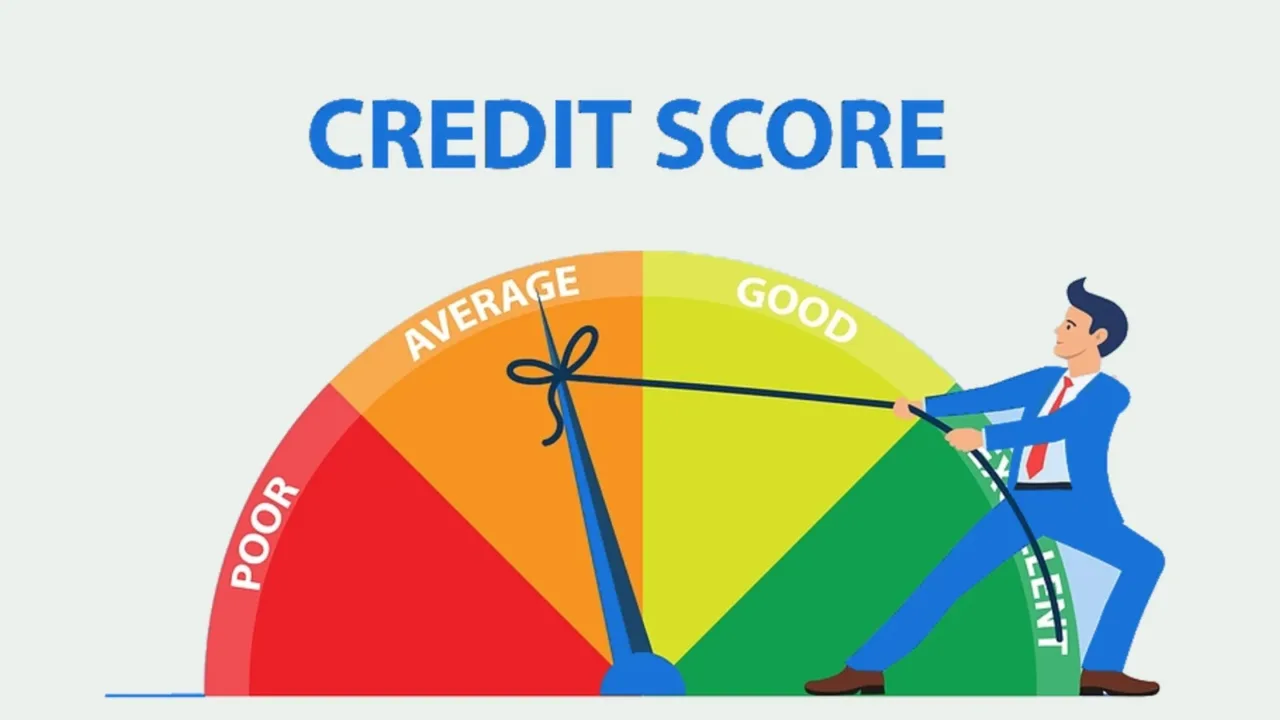
AECB Credit Score Ranges Explained
Understanding what constitutes a good, average, or poor financial score.
I analyzed the credit rating tier system to understand where my financial profile stands.
| Score Range | Rating Category | Financial Approval Odds |
| 300 – 619 | Very Low / Poor | High risk of credit rejections and loan denials |
| 620 – 679 | Low / Fair | Basic approvals with high interest rates |
| 680 – 729 | Good / Medium | Standard loan approvals and fair credit limits |
| 730 – 900 | Very Good / Excellent | Instant loan approvals and premium credit perks |
Key Factors That Drive Your Score Up or Down
The main financial behaviors that directly shape your credit rating.
Understanding how banks calculate your rating allows you to focus on high impact financial habits.
- Payment History: Timely payment history accounts for the largest portion of your overall score.
- Credit Utilization: Keeping your credit card balances low boosts your score significantly.
- Credit Type Mix: Managing personal loans, credit cards, and utility bills shows reliability.
- Hard Inquiries: Applying for multiple loans at once creates hard inquiries that lower scores.
Step by Step Action Plan to Elevate Your Score
Proven habits and smart strategies to rebuild your rating systematically.
I followed a strict action plan that helped me build a healthy financial profile within months.
- Set Up Auto Debits: Schedule automated bank transfers to pay loan EMIs and bills on time.
- Lower Balance Ratios: Keep overall credit card utilization below 30% of your total limit.
- Keep Old Cards Open: Maintain long standing credit cards to build an established history.
- Pay Utilities On Time: Pay DEWA, Etisalat, du, and rental cheques without bouncing.
Fixing Errors on Your Official Credit Report
How to download, inspect, and dispute inaccurate information on your profile.
I regularly review my official credit report to make sure phantom debts or errors do not pull down my score.
- Download the App: Install the official AECB app to download your updated report.
- Identify Errors: Check for incorrect personal details, closed accounts listed as open, or phantom debts.
- File Disputes: Submit official dispute requests through the AECB portal or issuing bank.
Common Pitfalls Expat Residents Must Avoid
Dangerous credit traps that cause sudden score drops.
Avoiding these common financial mistakes kept my credit score safe from unexpected drops.
- Multiple Credit Applications: Never apply for several credit cards simultaneously after a rejection.
- Maxing Out Limits: Avoid maxing out credit limits during shopping sales or holidays.
- Ignoring Small Balances: Never ignore tiny overdue fees on unused cards or phone lines.
- Co-Signing Loans: Refrain from co-signing loans or sharing credit cards with friends.
Timeline & Real Expectations for Score Recovery
How long it takes to see real improvements in your credit rating.
Rebuilding a credit profile requires patience because banks update data on specific monthly schedules.
- Data Update Cycles: Banks and utility providers report updates to AECB every 30 to 90 days.
- Rebuilding Timeline: Reaching a healthy 700+ score usually takes 3 to 6 months of disciplined payments.
- Long Term Consistency: Consistent on time payments permanently overwrite past financial delays.
Conclusion
Learning how I improve my AECB credit score in UAE transformed my financial standing, enabling seamless loan approvals and long term peace of mind.
ALSO READ:
- 10 Best Credit Cards in UAE for Beginners (2026 Guide)
- How to Open Bank Account in UAE Online 7 Powerful Steps for Fast & Easy Approval
FAQs
Does checking my own AECB score lower my rating?
No, self checks count as soft inquiries and never harm your score.
Do unpaid phone bills affect my credit score in UAE?
Yes, Etisalat and du report late payments directly to the AECB.
What credit card utilization ratio is ideal?
You should keep your balance below 30% of your total limit.
How often does the AECB update credit reports?
Financial institutions submit updated credit data every 30 to 90 days.
Can bounced cheques hurt my credit score?
Yes, rental and personal bounced cheques severely damage your rating.